What is the scope and industry significance of the Body Armor Plates Market?
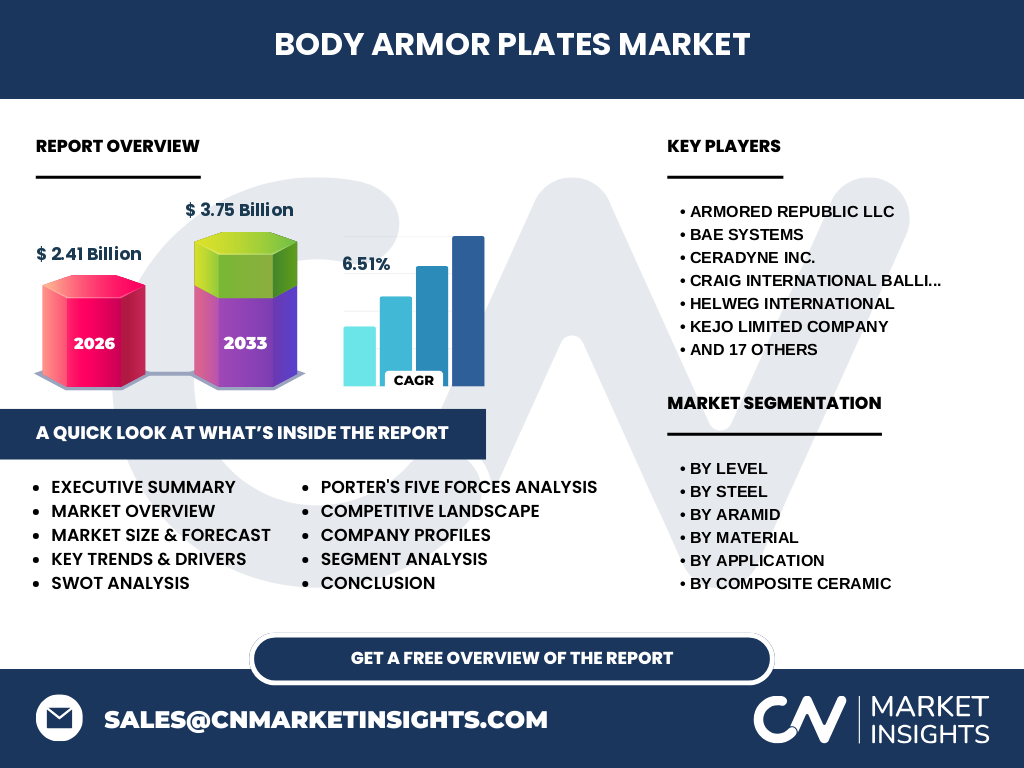
Our analysis indicates the Body Armor Plates Market encompasses ballistic insert plates governed by strict NIJ standards, scaling to reach 2.41 Billion in 2026. This sector protects military personnel and law enforcement against high-velocity rifle rounds using advanced materials.
Key market drivers, restraints, challenges, and opportunities shaping Body Armor Plates Market
Rising geopolitical tensions act as primary structural drivers, while supply chain constraints for high-modulus aramid fibers create operational bottlenecks. Growth opportunities lie in developing lightweight multi-curve steel and advanced ceramic composite plates for modern infantry.
Emerging trends and growth patterns in Body Armor Plates Market
The industry is shifting toward multi-hit UHMWPE multi-layer plates and ceramic tile configurations. Adept Armor and TenCate Advanced Armor lead this trend by minimizing backface deformation while reducing overall carrier weight.
How did COVID-19 impact the Body Armor Plates Market and what is the recovery trajectory?
The pandemic caused severe logistical disruptions across primary ports and raw material shortages for aramid and UHMWPE resins. Post-COVID recovery shows accelerated defense procurement cycles, stabilizing supply chains for major contractors like BAE Systems and Safariland LLC.
Competitive benchmarking and strategic dynamics in the Body Armor Plates Market
Market concentration remains moderately fragmented, featuring prime defense primes alongside specialized innovators like Spartan Armor Systems and Armored Republic LLC. Companies differentiate through proprietary ceramic sintering and specialized hard steel plate treatments.
Executive Summary: High-level synthesis of key findings about Body Armor Plates Market
Driven by rising defense budgets, the Body Armor Plates Market is projected to surge from 2.41 Billion in 2026 to 3.75 Billion by 2033, registering a robust CAGR of 6.51%.
Market forecast trajectory from 2027 to 2033
Based on our research, steady military modernization programs across NATO and allied nations will propel the market from 2027 through 2033, achieving an expansion rate defined by a 6.51% CAGR up to 3.75 Billion.
Segmentation analysis across material and protection levels
The sector is segmented by protection level (Level III, Level IV), materials (UHMWPE, Steel, Aramid, Composite Ceramic), and application (Defense, Law Enforcement, Civilians). Level IV ceramic composite plates dominate high-threat defense procurement.
Regional market analysis and geographic performance distribution
North America dominates demand due to extensive Department of Defense acquisitions, followed by Europe and the Asia-Pacific region. Localized defense manufacturing mandates heavily influence supplier selection in each respective geographic zone.
In-depth regional review of high-growth territories
The Asia-Pacific territory exhibits the fastest adoption rate, fueled by localized military modernization initiatives in India and Southeast Asia. Procurement prioritizes lightweight UHMWPE single-layer plates suited for tropical operating environments.
Strategic positioning of leading companies in Body Armor Plates Market
Industry stalwarts like Point Blank Enterprises Inc and Ceradyne Inc. leverage long-standing military contracts, while agile challengers such as Ace Link Armor and Chase Tactical capture civilian and law enforcement segments with rapid ecommerce fulfillment.
Porter's Five Forces analysis of competitive pressures
Supplier power is high due to specialized aramid and ceramic precursor scarcity, while buyer power remains moderate given stringent NIJ certification requirements. Threat of substitutes is low because certified ballistic protection requires rigorous laboratory testing.
SWOT analysis of the Body Armor Plates Market industry
Strengths include life-saving proprietary ballistic technologies; weaknesses involve high capital expenditure for ceramic sintering. Opportunities lie in civil-defense adoption, while threats stem from counterfeit plates entering secondary commercial distribution channels.
Value chain analysis from raw materials to end-users
The value chain flows from chemical polymer synthesis of UHMWPE and aramid fibers, through plate pressing by manufacturers like Kejo Limited Company, to distribution via tactical gear brands to defense end-users.
Investment insights and high-potential areas
Investors should target manufacturers specializing in multi-hit composite ceramic and advanced UHMWPE multi-layer plates. These segments offer superior margins and align directly with military demands for reduced soldier load carriage.
Conclusion and key takeaways for stakeholders
Reaching 3.75 Billion by 2033 at a 6.51% CAGR, the market rewards firms investing in advanced materials science. Regulatory compliance and supply chain resilience remain paramount for sustained profitability.
Research methodology for baseline estimates and data triangulation
Our findings combine primary stakeholder interviews with defense contractors, secondary trade registry data, and macroeconomic defense spending indicators to triangulate accurate market size valuations for 2026.
Scope of the report, coverage parameters, and limitations
This report covers global hard and soft ballistic insert plates across defense and civilian applications from 2026 to 2033. Limitations exclude classified black-budget military acquisitions outside public procurement records.
Recent developments, company announcements, and strategic moves
Recent industry activity highlights EnGarde Body Armor and Tough Hook expanding distribution partnerships, alongside Adept Armor launching ultra-high performance titanium-ceramic hybrid plates designed to defeat armor-piercing rounds.